FIRE calculator
FIRE (financial independence, retire early) means having enough invested to cover your spending for good, so work becomes optional.
Import from Trading 212, Degiro, IBKR and more, and see your real returns in one place.
How the FIRE calculator works
Your FIRE number
Yearly spending divided by the withdrawal rate. At 4% that's 25 times what you spend in a year.
Everything is in today's money
Inflation comes off your return, so €30,000 in 2050 buys what it buys now. That's why the FIRE number line stays flat.
Is 4% safe?
In US market history, 4% a year plus inflation lasted at least 30 years in almost every period. Stopping at 40 can mean 50 years, so many people plan with 3.5% or 3%.
Each quarter comes faster
With the default numbers, the last quarter takes just over half as long as the first. Early on your savings do the work; later the portfolio's own returns take over.
Markets don't move in a straight line
The chart assumes the same return every year. A crash in the first years after you stop hurts most, and a lower withdrawal rate gives you room for it.
What it leaves out
A pension that starts later means you need less from then on. Treat the result as a rough plan and come back to it every year.
Other kinds of FIRE
Lean FIRE
Retiring on a tight budget that covers the essentials. The FIRE number is smaller, so you get there sooner, with less room for surprises.
Fat FIRE
Enough to keep a comfortable life after you stop, with travel and a cushion. It takes longer and usually needs a high income.
Coast FIRE
You've invested enough that it grows into your FIRE number by retirement age with no more saving. You only need to earn what you spend today.
Coast FIRE calculatorBarista FIRE
You leave full-time work and part-time income covers some of your spending, so the portfolio can be smaller.
Barista FIRE calculatorRead more
Track the portfolio that gets you there
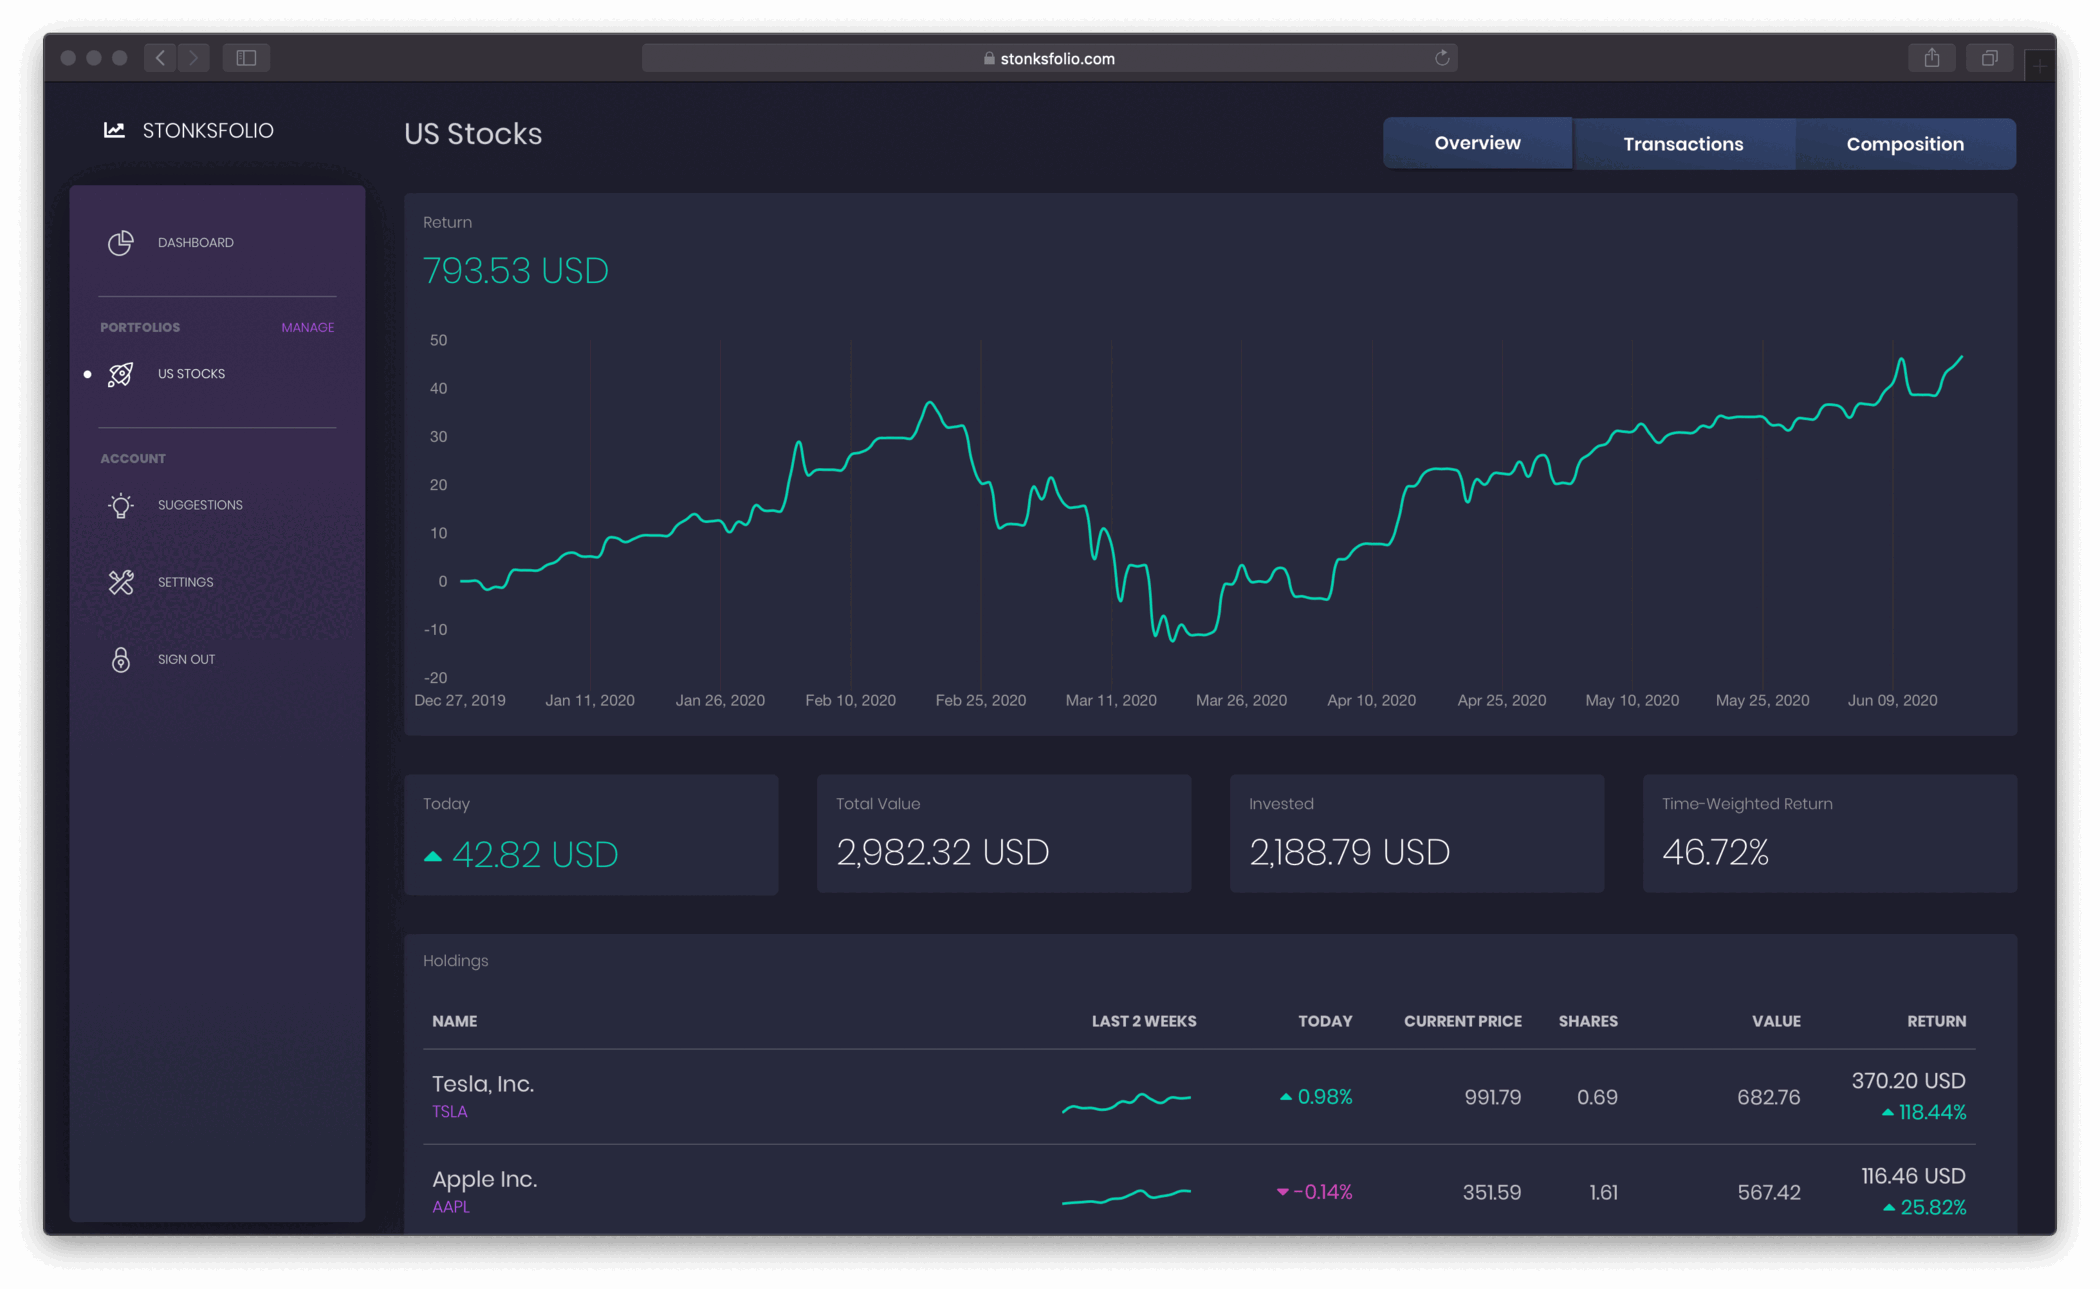
This calculator runs on the return you expect. Stonksfolio shows the one you're getting, across every broker you use.
- Your real returnTime-weighted, so deposits don't skew it. Check it against what you assumed here.
- Every broker in one placeImport from Trading 212, Degiro, Interactive Brokers and more.
- This month's buy ordersSet target weights, enter what you're adding, and get the exact orders.
- BenchmarksSee how you're doing against the S&P 500, MSCI World or gold.
Free to start. No credit card.